
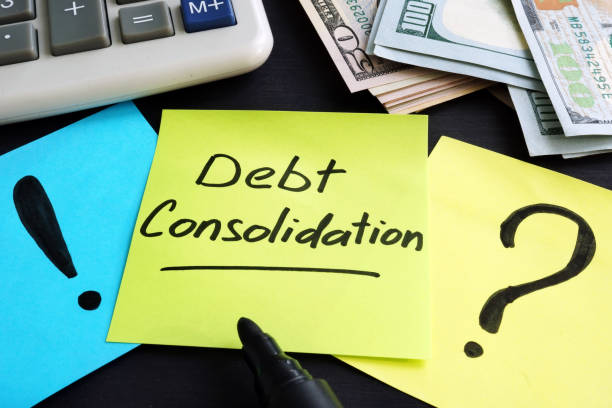
Carrying a handful of credit cards, a car loan, and maybe a line of credit all at once gets exhausting fast, especially when the interest on each one is quietly working against you every month. That’s usually the point where people start looking into Montreal debt consolidation as a way to simplify things. The basic idea is straightforward — you roll multiple debts into a single loan, ideally at a lower interest rate than what you were paying across those separate balances, and end up with one manageable payment instead of juggling five due dates. Homeowners often do this through a refinance or a secured line of credit against their property, since home equity tends to come with much better rates than unsecured credit card debt ever will. It’s not a magic fix, and it doesn’t erase what’s owed, but it can meaningfully lower what you’re paying in interest each month, which frees up cash for actually paying down the principal instead of treading water.
Why Homeowners Often Have The Best Options Here
Not everyone has home equity to work with, but for those who do, the math tends to work out considerably better than unsecured options. Credit card interest in Canada regularly sits north of 19%, sometimes higher, while a home equity loan or refinance might land somewhere in the single digits depending on rates at the time. That gap adds up fast, especially on larger balances. Someone carrying $30,000 across a couple of cards, for instance, could see their monthly interest cost drop dramatically just by shifting that debt onto their mortgage instead. This is a big part of why Montreal debt consolidation conversations so often start with a look at how much equity someone’s actually built up in their home, since that number pretty much determines what’s realistically on the table.
How This Connects to Home Renovation Financing
Interestingly, debt consolidation and home improvements often get tackled in the same conversation, since both usually involve tapping into equity. Someone dealing with a renovation mortgage Montreal lenders offer might discover along the way that rolling in some existing debt makes sense too, especially if they’re already refinancing to cover contractor costs. Combining both goals into a single mortgage adjustment can actually save on fees compared to doing two separate transactions down the road. That said, it’s worth being intentional here — using home equity for a kitchen remodel is different from using it to pay off debt that built up from day-to-day spending, and lenders will sometimes ask about the purpose to make sure the numbers actually make sense for your situation.

What Lenders Actually Look At Before Approving
Getting approved for a consolidation loan isn’t automatic, even with decent home equity sitting there. Lenders want to see your full financial picture — income stability, existing debt load relative to what you earn, and your credit history over the past few years, not just your current score. Someone with a spotty payment history might still qualify, but probably at a less favourable rate than someone with a clean track record. The loan-to-value ratio on the home matters a lot too, since lenders generally won’t let you borrow past a certain percentage of what the property’s actually worth. For anyone exploring Montreal debt consolidation seriously, gathering pay stubs, a list of current debts with balances, and a recent sense of your home’s value ahead of time tends to speed the whole process up considerably.
Mistakes People Make When Consolidating Debt
One of the most common slip-ups is consolidating debt and then continuing to use those old credit cards like nothing changed, which just leaves someone right back where they started, except now with a bigger mortgage on top of it. Another mistake is not comparing lenders before committing, since terms and rates on consolidation loans can vary more than people expect. Some folks also stretch the loan term out longer than necessary just to lower the monthly payment, without realizing that extending the timeline means paying more in interest overall, even at a lower rate. It’s also worth being cautious about rolling every single debt into a mortgage without checking whether some of it, like a low-interest car loan, was actually fine left where it was. Anyone weighing Montreal debt consolidation should really think through the full picture, not just the immediate relief of a lower monthly payment.
When It Might Make More Sense to Wait
Consolidation isn’t the right move for everyone, and timing matters more than people usually assume. If someone’s close to paying off most of their debt anyway, refinancing might cost more in fees than it actually saves. Similarly, if home values have dipped recently, there might not be enough equity available to make consolidation worthwhile without mortgage insurance eating into the savings. Anyone considering a renovation mortgage Montreal option alongside consolidation should also think about whether tackling both at once actually fits their budget, or whether it makes more sense to space these decisions out over a year or two. Talking through the numbers with someone who isn’t trying to sell a specific product tends to bring more clarity here than guessing on your own.
Conclusion
Debt can pile up quietly, and by the time it feels overwhelming, most people just want a clear, realistic plan rather than more confusing options thrown at them. Whether that plan involves rolling debt into your mortgage, financing a renovation, or some combination of both, having someone walk through the actual numbers with you makes a real difference. The team at Best Mortgage Montreal works with homeowners exploring both consolidation and renovation mortgage Montreal options, helping figure out what genuinely fits your finances rather than pushing a one-size-fits-all solution.
FAQ
Will consolidating my debt hurt my credit score?
There might be a small, temporary dip from the credit check involved, but paying down high-interest debt generally helps your score over time.
Can I consolidate debt without owning a home?
Yes, though options are usually more limited and rates less favourable compared to using home equity as security.
Is there a minimum amount of equity needed to consolidate?
It varies by lender, but most want to see enough equity that your total borrowing stays within a certain percentage of the home’s value.
Can I combine a renovation loan with debt consolidation?
Often yes, and doing both together can sometimes save on fees compared to handling them as two separate transactions.
How long does the consolidation process usually take?
It depends on your paperwork and the lender, but many straightforward cases close within a few weeks once documents are submitted.